9 min
9 min
Private Wealth Management Companies in Delhi NCR (2026 Guide)
Private Wealth Management Companies in Delhi NCR (2026 Guide)
Private Wealth Management Companies in Delhi NCR (2026 Guide)
Private wealth management companies serving Delhi NCR, listed unranked, plus the six checks and three questions that turn a long list into a shortlist.
Private wealth management companies serving Delhi NCR, listed unranked, plus the six checks and three questions that turn a long list into a shortlist.
Private wealth management companies serving Delhi NCR, listed unranked, plus the six checks and three questions that turn a long list into a shortlist.

Ckredence Wealth
Ckredence Wealth
|
The Short Version
Private wealth management companies serving Delhi NCR fall into four structural types. These are national bank and AMC wealth arms, independent private-wealth boutiques, digital-first platforms, and regional full-service firms serving the region remotely.
The type matters more than the brand.
Which type suits you comes down to two things: your ticket size, and whether your advice is paid for by you or by a product manufacturer. That second distinction is where most Delhi NCR investors get it wrong. A firm can call itself a wealth manager while earning its living from commissions. Both types appear on the same search results page, and neither label is visible from the outside.
This guide names the firms that serve the region, lists them without ranking, and gives you the checks that actually separate them. The list is the easy part. The criteria are what save you a bad decade.
TL; DR1. Private wealth firms serving Delhi NCR split into four types: bank and AMC wealth arms, independent boutiques, digital-first platforms, and regional full-service firms 2. The single most consequential question is whether a firm is a distributor, a SEBI Registered Investment Adviser, or both. It decides who pays for the advice 3. India had 515 SEBI-registered portfolio managers as of 31 May 2026, more than double the 226 registered in 2020 4. Assets-under-management league tables are a poor filter, because most reported PMS AUM is institutional retirement money rather than private-client money 5. Minimums range from roughly Rs 10 lakh for advisory mandates to Rs 50 lakh for a discretionary PMS, the latter a statutory SEBI floor 6. Every registration claim on this page, and on any firm's own site, is verifiable on the SEBI and AMFI registers in about two minutes 7. SEBI published a consultation paper in July 2026 that may change entry thresholds, so confirm current rules before committing capital |
See where your current wealth arrangement actually stands before you shortlist anyone.
What Should You Check Before Shortlisting a Wealth Management Company in Delhi NCR?
Run these six checks before you look at any list, including the one below. They are ordered so the cheapest and most disqualifying checks come first.
# | Check | Where to verify |
1 | Registration type: Portfolio Manager, RIA, AMFI distributor, or a combination | SEBI register, not the firm's website |
2 | Who pays for the advice: you, or the product manufacturer | Ask in writing, per mandate |
3 | The complaint record | SEBI's SCORES portal, public and searchable |
4 | Minimum ticket, and where you sit relative to it | Ask directly |
5 | Who handles your file, and who else knows it | Ask directly |
6 | Reporting: a redacted sample statement | Ask before signing |
💡 For investors comparing more than three firms Score every firm on the same six checks in one spreadsheet before any meeting. Meetings are built to be persuasive, and a criteria sheet made beforehand is the only reliable defence against a good pitch. |
What Are Some Reputable Wealth Management Companies in Delhi NCR?
The firms below serve Delhi NCR either through a local office or remotely. They are listed alphabetically and not ranked. No evaluation, scoring or recommendation is offered or implied.
Positioning is as each firm describes itself publicly as of September 2026. Registration status, minimums and fee structures change, so treat every row as a starting point for your own verification.
Firm | Structural type | How it positions itself publicly | What to verify yourself |
360 ONE | National private-wealth platform | Private wealth management for HNI and UHNW families | Current licences, minimum, fee model |
Anand Rathi Wealth | National private-wealth arm | Private wealth for HNI and UHNI families | Licences, whether advisory or distribution led |
ASK Private Wealth | National, PMS-affiliated | Wealth and portfolio management for HNIs | PMS registration, minimum ticket |
Regional full-service, Surat headquartered | SEBI-registered Portfolio Manager and Investment Adviser serving investors outside Gujarat remotely | PMS INP000007164, RIA INA000020846, minimum, fee model | |
Dezerv | Digital-first platform | Technology-led managed portfolios and PMS access | Licences, whether adviser or distributor |
Motilal Oswal Private Wealth | AMC-affiliated wealth arm | Private wealth management for HNI clients | Licences, product-shelf breadth, fee model |
Nuvama Private | National private-wealth platform | Wealth management for HNI and UHNW segments | Licences, minimum, fee model |
Spark Capital Private Wealth | Independent boutique | Private wealth management and investment advisory | Licences, minimum, fee model |
Where Ckredence Sits on the Delhi NCR List
Ckredence appears here on the same terms as every other entry, with the same verification column and no ranking. It is headquartered in Surat and does not maintain an office in Delhi NCR; this page will not suggest otherwise. What it does hold is both a Portfolio Manager and an Investment Adviser registration under one roof. That combination is less common than the list above makes it look.
The Situation We See Most Often in Delhi NCR
A promoter in his fifties, a portfolio in the Rs 3-5 crore range, built across a decade of separate decisions. Equity with one firm, insurance-linked products sold by a second, and a mutual fund book with a third. Nobody held the whole picture, so nobody could say whether the overall position still matched the plan. Consolidating the reporting came before any advice was given. Situation described is illustrative of a client engagement pattern and does not indicate results for any other investor. |
If your portfolio, advice and reporting sit with more than one firm, a fee-only mandate can put it under one view.
Why This Delhi NCR List Is Short and Unranked
Directory sites and job boards dominate this search result because they publish long, unfiltered lists. A longer list is not a better one. For the complete population, the SEBI and AMFI registers are the only authoritative sources; for the underlying service distinction, see what wealth management actually covers.
How Was This Delhi NCR List Compiled?
Stating the method matters more than the list, because it lets you rebuild the list yourself with different criteria.
Element | Method used |
Inclusion / exclusion | Page-one Google results for private wealth queries scoped to Delhi NCR, September 2026, filtered to actual service providers. Directories and job boards excluded; no firm excluded on quality grounds |
Ordering | Alphabetical. No ranking, scoring or weighting applied |
Deliberately excluded | AUM, client counts and minimum tickets, since self-reported figures are inconsistently defined and go stale |
Status | Not a recommendation. Appearance is not an endorsement, and absence is not a criticism |
If your criteria differ, our note on assessing financial advisory services in India sets out alternative filters.
What Is the Difference Between a Wealth Manager and a Financial Advisor?
In India the difference is regulatory, not descriptive. "Wealth manager" is a job title with no licensing meaning. "Investment Adviser" and "Portfolio Manager" are separate SEBI registrations. The first carries a fiduciary duty. The second permits discretionary management in your own demat account. Ask which registration the firm acts under, in writing, for your specific mandate.
Our comparison of wealth management versus portfolio management sets out where the two overlap.
What Is the Minimum for Wealth Management in India?
There is no single minimum. The figure depends on which service you are buying, not which firm you approach.
Service | Typical entry point | Who sets it |
Advisory mandates | Rs 10 lakh to Rs 25 lakh | Each firm, not regulation |
Discretionary Portfolio Management Services | Rs 50 lakh, statutory | SEBI. No registered portfolio manager can go below it |
Private wealth / family-office relationships | Rs 5 crore and above, at larger national firms | Each firm, rarely published |
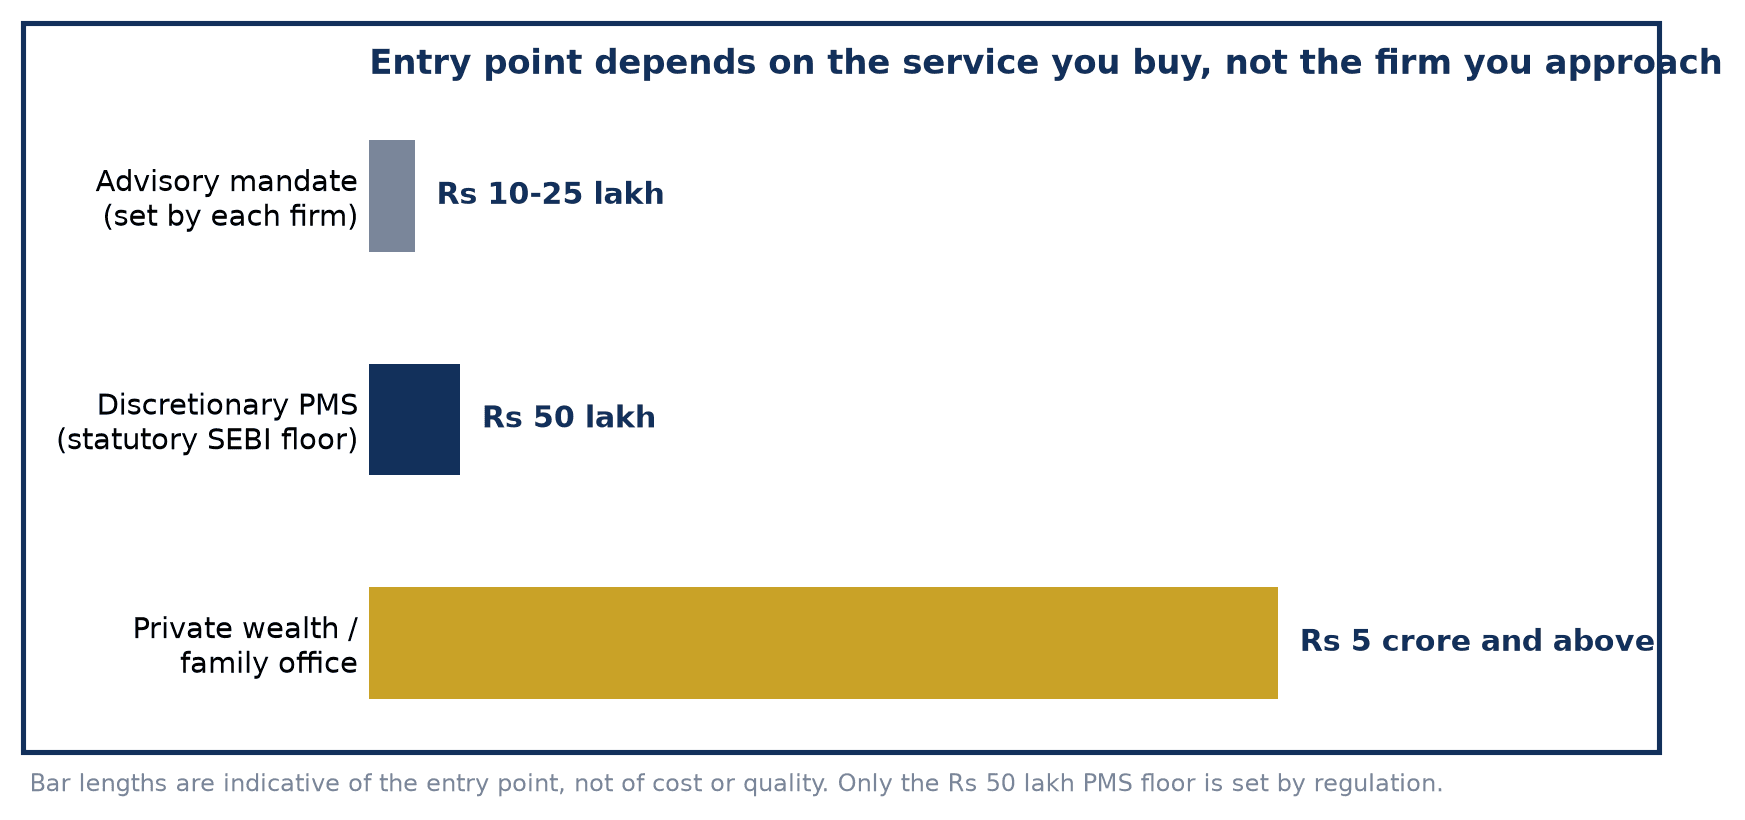 |
Entry point depends on the service you buy, not the firm you approach
Bar lengths are indicative of the entry point only, not of cost or quality. Only the Rs 50 lakh PMS floor is set by regulation.
An offer to run a discretionary PMS below the Rs 50 lakh floor is a serious warning sign, whichever firm makes it.
📊 515 registered portfolio managers in India Up from 226 in 2020, alongside industry AUM of Rs 42.61 lakh crore and 2.19 lakh total clients. The licensed population has more than doubled in six years. *Source: India Corporate Law, Cyril Amarchand Mangaldas, as of 31 May 2026* |
SEBI's consultation paper of 23 July 2026 proposed a category at a reduced entry threshold. Comments closed 13 August 2026, unsettled at the time of writing. Our note on the Rs 50 lakh PMS threshold covers who the current floor suits.
What Is the Typical Fee for a Wealth Manager in Delhi NCR?
Fees take three shapes in the Indian market, and the shape tells you more than the number.
Fee shape | How it works | What to watch |
Commission-based | The product manufacturer pays the firm, embedded in the expense ratio | You never see an invoice, which is precisely the problem |
Fee-only advisory | You pay a retainer or a percentage of assets advised, typically under 1% | Under SEBI RIA rules the firm cannot also take commission on advised assets |
Discretionary PMS | A fixed annual fee plus a performance-linked profit share above a hurdle | An exit load that tapers over two to three years sits on top |
Comparing the headline percentage across these three is meaningless. Compare total annual cost in rupees on your actual corpus instead. Ask each firm to produce that single figure; most will not have it ready, and how they respond is informative. Our breakdown of PMS charges and fee structures shows the full arithmetic.
The Three-Question Shortlist Test
Ten firms is not a shortlist. Three questions, asked on a first call, will usually get you to two.
# | Ask this | Why it works | What a poor answer looks like |
1 | For my mandate, are you a distributor, a SEBI Registered Investment Adviser, or both? | Establishes who pays for the advice. Highest-value, least-asked question in Indian wealth management | Vagueness on which capacity applies to which recommendation |
2 | What is your minimum, and where would my corpus sit relative to your average client? | The second half determines the service you will actually receive | No answer on the second half |
3 | Besides my relationship manager, who else knows my file? | Tests continuity; RM turnover is the most common source of service failure | Exactly one person |
⚠️ Risk to understand All three answers should come without hesitation and without being checked. A firm that needs to come back to you on question one is telling you the answer is complicated in a way that will not work in your favour. |
The Assumption Is That the Biggest Firm Is the Safest Choice
The reality cuts in both directions. Scale genuinely buys research depth, operational resilience and product access, but what scale does not buy is attention proportional to your corpus. At a firm whose typical relationship is Rs 10 crore, a Rs 60 lakh mandate is serviced by the most junior person available. At a firm whose typical relationship is Rs 1 crore, the same mandate is a core client. Asset-based league tables tell you nothing about which one you are buying.
The Measurement Trap Underneath the League Tables
Reported PMS industry AUM reached Rs 43.3 lakh crore in June 2026. Business Today's analysis of APMI data, as of 30 June 2026, tells a different story. Rs 31.04 lakh crore of that, close to 85%, belongs to the EPFO and other provident funds, not individual investors.
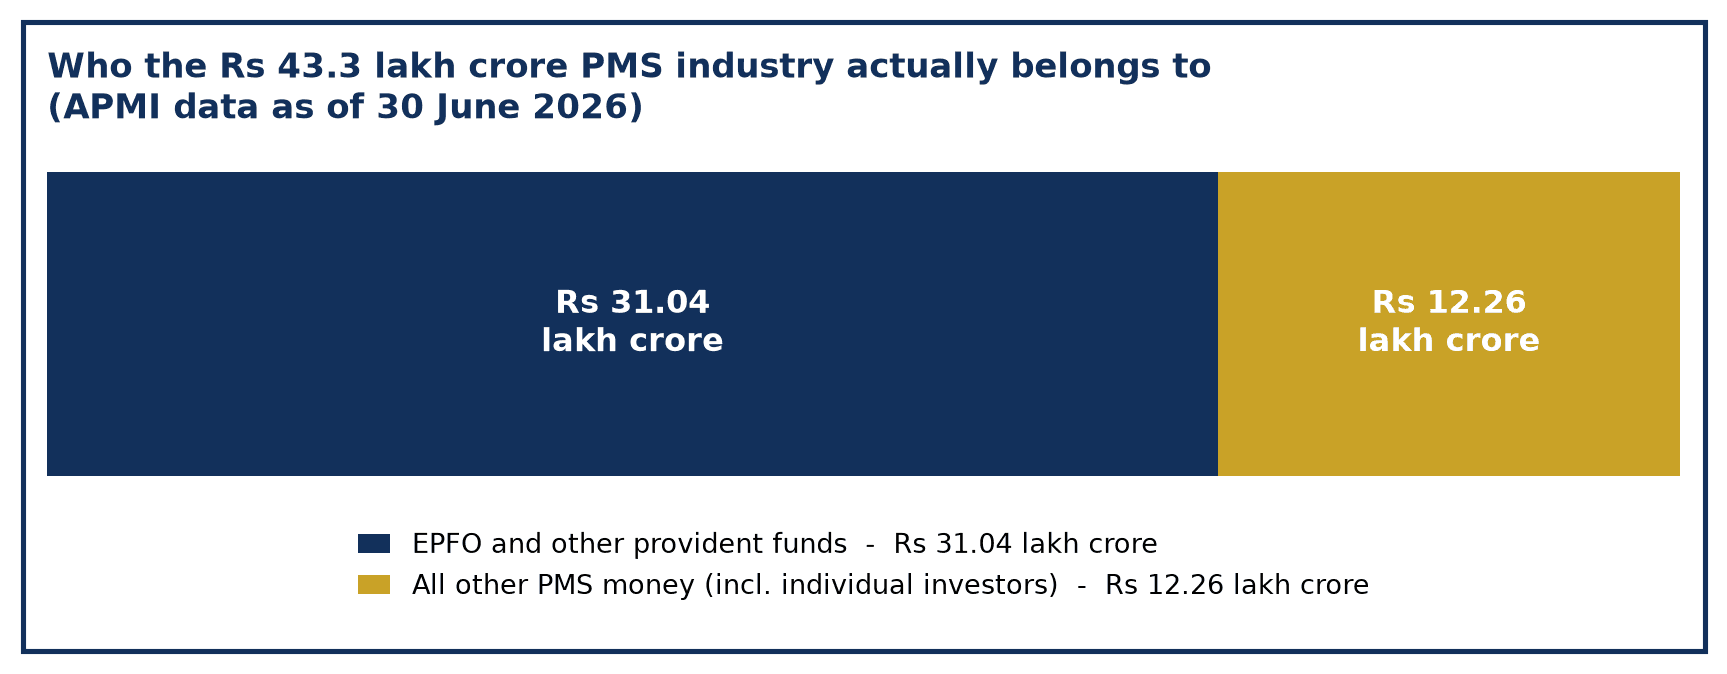 |
Who the Rs 43.3 lakh crore PMS industry actually belongs to
Source: Business Today's analysis of APMI data, as of 30 June 2026.
Ask how many individual discretionary clients a firm actually manages. What we see across long relationships is that retention tracks one thing. It is whether the investor got a clear, unhurried answer the first time something went wrong, usually inside the first eighteen months.
What Is a Red Flag for a Financial Advisor?
Several, and most are visible before you sign anything.
Any assurance about returns. A registered intermediary cannot guarantee performance
A registration number that does not reconcile on the SEBI register, or reluctance to state one at all
A recommendation made before your liabilities and time horizon are documented
Pressure tied to a deadline, a closing tranche, or an expiring allocation
Discouragement from getting a second opinion
⚠️ Risk to understand The most expensive red flag is the most comfortable one. An adviser who agrees with everything you already believe is not adding value, and concentrated or inherited portfolios are where an agreeable adviser causes the most damage. |
Who Should Not Hire a Private Wealth Manager?
Worth saying plainly, because a good deal of demand for this service is misdirected.
If this describes you | Better direction |
Below roughly Rs 25 lakh in investable assets | A low-cost index or mutual-fund portfolio usually outperforms the same portfolio minus a fee |
You want to retain every decision | Advisory or non-discretionary, not a discretionary mandate |
You are seeking a specific return | No registered firm can promise one; reset the expectation first |
You have one concentrated need, not an ongoing mandate | A chartered accountant or specialist |
You will move on a bad quarter | Stay unmanaged until the horizon is real; exiting mid-drawdown locks in the loss |
For investors above roughly Rs 25 crore with multi-generational needs, see our note on multi-family offices in India.
Conclusion
The list of private wealth management companies serving Delhi NCR is short, public and easy to assemble. It is also the least useful part of the decision. Every firm on it will present well.
What will matter over the next decade is which licence the firm acts under and who pays for the advice. It is also where your corpus sits relative to the firm's typical client, and who besides one relationship manager understands your file. Those four things are answerable on a single phone call.
Do this work before the meetings rather than after them, and the shortlist takes care of itself.
Frequently Asked Questions
What are the top 10 private wealth management firms in India?
No credible single ranking exists, because the firms are not comparable on one axis. A firm managing Rs 50,000 crore of institutional mandates and a boutique managing Rs 800 crore of private-client money are different businesses. Build a shortlist against your own criteria instead: registration type, who pays for the advice, and minimum ticket relative to your corpus.
Which company is best for wealth management?
There is no single best firm, because suitability depends on your corpus, the decision rights you want to retain, and your time horizon. A fee-only adviser suits an investor who wants conflict-free guidance while keeping control; a discretionary portfolio manager suits one who wants professional management through volatility.
Who are the biggest wealth management companies?
Measured by reported AUM, the largest players are the bank and AMC-affiliated wealth arms and the large national platforms. That measure is misleading for private clients, since a large share of reported PMS assets is institutional retirement money rather than individual portfolios.
What is the minimum for wealth management?
It depends on the service. Advisory mandates commonly start between Rs 10 lakh and Rs 25 lakh. Discretionary Portfolio Management Services carry a statutory minimum of Rs 50 lakh, set by SEBI.
The Short Version
Private wealth management companies serving Delhi NCR fall into four structural types. These are national bank and AMC wealth arms, independent private-wealth boutiques, digital-first platforms, and regional full-service firms serving the region remotely.
The type matters more than the brand.
Which type suits you comes down to two things: your ticket size, and whether your advice is paid for by you or by a product manufacturer. That second distinction is where most Delhi NCR investors get it wrong. A firm can call itself a wealth manager while earning its living from commissions. Both types appear on the same search results page, and neither label is visible from the outside.
This guide names the firms that serve the region, lists them without ranking, and gives you the checks that actually separate them. The list is the easy part. The criteria are what save you a bad decade.
TL; DR1. Private wealth firms serving Delhi NCR split into four types: bank and AMC wealth arms, independent boutiques, digital-first platforms, and regional full-service firms 2. The single most consequential question is whether a firm is a distributor, a SEBI Registered Investment Adviser, or both. It decides who pays for the advice 3. India had 515 SEBI-registered portfolio managers as of 31 May 2026, more than double the 226 registered in 2020 4. Assets-under-management league tables are a poor filter, because most reported PMS AUM is institutional retirement money rather than private-client money 5. Minimums range from roughly Rs 10 lakh for advisory mandates to Rs 50 lakh for a discretionary PMS, the latter a statutory SEBI floor 6. Every registration claim on this page, and on any firm's own site, is verifiable on the SEBI and AMFI registers in about two minutes 7. SEBI published a consultation paper in July 2026 that may change entry thresholds, so confirm current rules before committing capital |
See where your current wealth arrangement actually stands before you shortlist anyone.
What Should You Check Before Shortlisting a Wealth Management Company in Delhi NCR?
Run these six checks before you look at any list, including the one below. They are ordered so the cheapest and most disqualifying checks come first.
# | Check | Where to verify |
1 | Registration type: Portfolio Manager, RIA, AMFI distributor, or a combination | SEBI register, not the firm's website |
2 | Who pays for the advice: you, or the product manufacturer | Ask in writing, per mandate |
3 | The complaint record | SEBI's SCORES portal, public and searchable |
4 | Minimum ticket, and where you sit relative to it | Ask directly |
5 | Who handles your file, and who else knows it | Ask directly |
6 | Reporting: a redacted sample statement | Ask before signing |
💡 For investors comparing more than three firms Score every firm on the same six checks in one spreadsheet before any meeting. Meetings are built to be persuasive, and a criteria sheet made beforehand is the only reliable defence against a good pitch. |
What Are Some Reputable Wealth Management Companies in Delhi NCR?
The firms below serve Delhi NCR either through a local office or remotely. They are listed alphabetically and not ranked. No evaluation, scoring or recommendation is offered or implied.
Positioning is as each firm describes itself publicly as of September 2026. Registration status, minimums and fee structures change, so treat every row as a starting point for your own verification.
Firm | Structural type | How it positions itself publicly | What to verify yourself |
360 ONE | National private-wealth platform | Private wealth management for HNI and UHNW families | Current licences, minimum, fee model |
Anand Rathi Wealth | National private-wealth arm | Private wealth for HNI and UHNI families | Licences, whether advisory or distribution led |
ASK Private Wealth | National, PMS-affiliated | Wealth and portfolio management for HNIs | PMS registration, minimum ticket |
Regional full-service, Surat headquartered | SEBI-registered Portfolio Manager and Investment Adviser serving investors outside Gujarat remotely | PMS INP000007164, RIA INA000020846, minimum, fee model | |
Dezerv | Digital-first platform | Technology-led managed portfolios and PMS access | Licences, whether adviser or distributor |
Motilal Oswal Private Wealth | AMC-affiliated wealth arm | Private wealth management for HNI clients | Licences, product-shelf breadth, fee model |
Nuvama Private | National private-wealth platform | Wealth management for HNI and UHNW segments | Licences, minimum, fee model |
Spark Capital Private Wealth | Independent boutique | Private wealth management and investment advisory | Licences, minimum, fee model |
Where Ckredence Sits on the Delhi NCR List
Ckredence appears here on the same terms as every other entry, with the same verification column and no ranking. It is headquartered in Surat and does not maintain an office in Delhi NCR; this page will not suggest otherwise. What it does hold is both a Portfolio Manager and an Investment Adviser registration under one roof. That combination is less common than the list above makes it look.
The Situation We See Most Often in Delhi NCR
A promoter in his fifties, a portfolio in the Rs 3-5 crore range, built across a decade of separate decisions. Equity with one firm, insurance-linked products sold by a second, and a mutual fund book with a third. Nobody held the whole picture, so nobody could say whether the overall position still matched the plan. Consolidating the reporting came before any advice was given. Situation described is illustrative of a client engagement pattern and does not indicate results for any other investor. |
If your portfolio, advice and reporting sit with more than one firm, a fee-only mandate can put it under one view.
Why This Delhi NCR List Is Short and Unranked
Directory sites and job boards dominate this search result because they publish long, unfiltered lists. A longer list is not a better one. For the complete population, the SEBI and AMFI registers are the only authoritative sources; for the underlying service distinction, see what wealth management actually covers.
How Was This Delhi NCR List Compiled?
Stating the method matters more than the list, because it lets you rebuild the list yourself with different criteria.
Element | Method used |
Inclusion / exclusion | Page-one Google results for private wealth queries scoped to Delhi NCR, September 2026, filtered to actual service providers. Directories and job boards excluded; no firm excluded on quality grounds |
Ordering | Alphabetical. No ranking, scoring or weighting applied |
Deliberately excluded | AUM, client counts and minimum tickets, since self-reported figures are inconsistently defined and go stale |
Status | Not a recommendation. Appearance is not an endorsement, and absence is not a criticism |
If your criteria differ, our note on assessing financial advisory services in India sets out alternative filters.
What Is the Difference Between a Wealth Manager and a Financial Advisor?
In India the difference is regulatory, not descriptive. "Wealth manager" is a job title with no licensing meaning. "Investment Adviser" and "Portfolio Manager" are separate SEBI registrations. The first carries a fiduciary duty. The second permits discretionary management in your own demat account. Ask which registration the firm acts under, in writing, for your specific mandate.
Our comparison of wealth management versus portfolio management sets out where the two overlap.
What Is the Minimum for Wealth Management in India?
There is no single minimum. The figure depends on which service you are buying, not which firm you approach.
Service | Typical entry point | Who sets it |
Advisory mandates | Rs 10 lakh to Rs 25 lakh | Each firm, not regulation |
Discretionary Portfolio Management Services | Rs 50 lakh, statutory | SEBI. No registered portfolio manager can go below it |
Private wealth / family-office relationships | Rs 5 crore and above, at larger national firms | Each firm, rarely published |
|
Entry point depends on the service you buy, not the firm you approach
Bar lengths are indicative of the entry point only, not of cost or quality. Only the Rs 50 lakh PMS floor is set by regulation.
An offer to run a discretionary PMS below the Rs 50 lakh floor is a serious warning sign, whichever firm makes it.
📊 515 registered portfolio managers in India Up from 226 in 2020, alongside industry AUM of Rs 42.61 lakh crore and 2.19 lakh total clients. The licensed population has more than doubled in six years. *Source: India Corporate Law, Cyril Amarchand Mangaldas, as of 31 May 2026* |
SEBI's consultation paper of 23 July 2026 proposed a category at a reduced entry threshold. Comments closed 13 August 2026, unsettled at the time of writing. Our note on the Rs 50 lakh PMS threshold covers who the current floor suits.
What Is the Typical Fee for a Wealth Manager in Delhi NCR?
Fees take three shapes in the Indian market, and the shape tells you more than the number.
Fee shape | How it works | What to watch |
Commission-based | The product manufacturer pays the firm, embedded in the expense ratio | You never see an invoice, which is precisely the problem |
Fee-only advisory | You pay a retainer or a percentage of assets advised, typically under 1% | Under SEBI RIA rules the firm cannot also take commission on advised assets |
Discretionary PMS | A fixed annual fee plus a performance-linked profit share above a hurdle | An exit load that tapers over two to three years sits on top |
Comparing the headline percentage across these three is meaningless. Compare total annual cost in rupees on your actual corpus instead. Ask each firm to produce that single figure; most will not have it ready, and how they respond is informative. Our breakdown of PMS charges and fee structures shows the full arithmetic.
The Three-Question Shortlist Test
Ten firms is not a shortlist. Three questions, asked on a first call, will usually get you to two.
# | Ask this | Why it works | What a poor answer looks like |
1 | For my mandate, are you a distributor, a SEBI Registered Investment Adviser, or both? | Establishes who pays for the advice. Highest-value, least-asked question in Indian wealth management | Vagueness on which capacity applies to which recommendation |
2 | What is your minimum, and where would my corpus sit relative to your average client? | The second half determines the service you will actually receive | No answer on the second half |
3 | Besides my relationship manager, who else knows my file? | Tests continuity; RM turnover is the most common source of service failure | Exactly one person |
⚠️ Risk to understand All three answers should come without hesitation and without being checked. A firm that needs to come back to you on question one is telling you the answer is complicated in a way that will not work in your favour. |
The Assumption Is That the Biggest Firm Is the Safest Choice
The reality cuts in both directions. Scale genuinely buys research depth, operational resilience and product access, but what scale does not buy is attention proportional to your corpus. At a firm whose typical relationship is Rs 10 crore, a Rs 60 lakh mandate is serviced by the most junior person available. At a firm whose typical relationship is Rs 1 crore, the same mandate is a core client. Asset-based league tables tell you nothing about which one you are buying.
The Measurement Trap Underneath the League Tables
Reported PMS industry AUM reached Rs 43.3 lakh crore in June 2026. Business Today's analysis of APMI data, as of 30 June 2026, tells a different story. Rs 31.04 lakh crore of that, close to 85%, belongs to the EPFO and other provident funds, not individual investors.
|
Who the Rs 43.3 lakh crore PMS industry actually belongs to
Source: Business Today's analysis of APMI data, as of 30 June 2026.
Ask how many individual discretionary clients a firm actually manages. What we see across long relationships is that retention tracks one thing. It is whether the investor got a clear, unhurried answer the first time something went wrong, usually inside the first eighteen months.
What Is a Red Flag for a Financial Advisor?
Several, and most are visible before you sign anything.
Any assurance about returns. A registered intermediary cannot guarantee performance
A registration number that does not reconcile on the SEBI register, or reluctance to state one at all
A recommendation made before your liabilities and time horizon are documented
Pressure tied to a deadline, a closing tranche, or an expiring allocation
Discouragement from getting a second opinion
⚠️ Risk to understand The most expensive red flag is the most comfortable one. An adviser who agrees with everything you already believe is not adding value, and concentrated or inherited portfolios are where an agreeable adviser causes the most damage. |
Who Should Not Hire a Private Wealth Manager?
Worth saying plainly, because a good deal of demand for this service is misdirected.
If this describes you | Better direction |
Below roughly Rs 25 lakh in investable assets | A low-cost index or mutual-fund portfolio usually outperforms the same portfolio minus a fee |
You want to retain every decision | Advisory or non-discretionary, not a discretionary mandate |
You are seeking a specific return | No registered firm can promise one; reset the expectation first |
You have one concentrated need, not an ongoing mandate | A chartered accountant or specialist |
You will move on a bad quarter | Stay unmanaged until the horizon is real; exiting mid-drawdown locks in the loss |
For investors above roughly Rs 25 crore with multi-generational needs, see our note on multi-family offices in India.
Conclusion
The list of private wealth management companies serving Delhi NCR is short, public and easy to assemble. It is also the least useful part of the decision. Every firm on it will present well.
What will matter over the next decade is which licence the firm acts under and who pays for the advice. It is also where your corpus sits relative to the firm's typical client, and who besides one relationship manager understands your file. Those four things are answerable on a single phone call.
Do this work before the meetings rather than after them, and the shortlist takes care of itself.
Frequently Asked Questions
What are the top 10 private wealth management firms in India?
No credible single ranking exists, because the firms are not comparable on one axis. A firm managing Rs 50,000 crore of institutional mandates and a boutique managing Rs 800 crore of private-client money are different businesses. Build a shortlist against your own criteria instead: registration type, who pays for the advice, and minimum ticket relative to your corpus.
Which company is best for wealth management?
There is no single best firm, because suitability depends on your corpus, the decision rights you want to retain, and your time horizon. A fee-only adviser suits an investor who wants conflict-free guidance while keeping control; a discretionary portfolio manager suits one who wants professional management through volatility.
Who are the biggest wealth management companies?
Measured by reported AUM, the largest players are the bank and AMC-affiliated wealth arms and the large national platforms. That measure is misleading for private clients, since a large share of reported PMS assets is institutional retirement money rather than individual portfolios.
What is the minimum for wealth management?
It depends on the service. Advisory mandates commonly start between Rs 10 lakh and Rs 25 lakh. Discretionary Portfolio Management Services carry a statutory minimum of Rs 50 lakh, set by SEBI.